
Organizations need efficient business processes and robust technologies to remain competitive. Warren Whitney provides a variety of fractional and project based management services to help businesses improve operational efficiency, adapt to industry changes, and prepare for continued growth. Our professionals typically assist clients with strategic needs, but we can also roll up our sleeves and help drive tactics once the strategies are in place. Examples of services we provide are:
Contributor: Beth Williams
Today in business, there are more acronyms, legal agencies and regulatory requirements than ever before. If you employ people in your business, you must understand and comply with some of these requirements, many of which can be daunting. The number of people on your payroll will determine the magnitude of your time involved and, ultimately, the work expended to comply with the requirements. The full life cycle of an employee from recruiting strategies through terminations and all actions in between, present opportunities for a lawsuit. The key is creating best practice processes, policies and a workplace culture that protects your company and manages risk.rements than ever before. AND they just keep on coming with the impact of the Affordable Care Act (ACA) and the Fair Labor Standards Act (FLSA) being at the forefront this year for many employers.
Contributor: David Nelms
The following is a paraphrase of conversations I’ve had with several business owners and CFO’s recently. Does some or all of this apply to you and your business?
“My business is growing. The software we use is outdated, and the vendor we use doesn’t support it well anymore. We use a lot of Excel spreadsheets, but they are increasingly difficult to keep up with and are causing us a lot of problems. I’m having a hard time getting the information I need to manage the business. I know I need better tools and a more current system, but I don’t know where to start or how to find what we need. What do I do?“
Contributor: Stephanie Ford
Imagine this…. Your company is growing… you need capital to continue to expand… however, you’ve been turned down by three banks in a row. Yikes! Has this ever happened to you?
In my 12 years of experience as a commercial banker, the better prepared a business owner was for the request, the more likely they would receive financing. Owners that came to me with a binder chocked full of financial statements, detailed reports, and maybe even a strategic business plan were impressive. Entrepreneurs that provided few concrete materials and simply shared a stream of consciousness of their ideas gave me little to work with.
How to position yourself to get funding for your business is critical in today’s tight credit markets. Preparing a request for financing should be taken seriously, and good preparation will yield better results. Here is a framework for thinking about your approach.
1. Think hard about why you need to borrow. Specifically identify the purpose and develop a business case for the need to borrow and repayment. The best way to do this is to prepare monthly cash flow projections of sources and uses of cash. This prediction of needs and surplus will help to identify how much you need to borrow and how quickly your business can repay the loan. The purpose of your borrowing need will also help to determine what type of loan is best for your company, such as a revolving line of credit for working capital needs or a term loan for permanent improvements to real estate or equipment purchases.
2. The more complete a package of information you can provide to the bank, the better. If you have a business plan, share the entire plan with your banker. In addition to 3 years of financial statements and tax returns, also include any other key reports that you use to run your business. This may seem excessive, but even routine reports such as an accounts receivable aging and accounts payable aging aid in giving the banker insight to your customer management and diversification. Be sure to share any key metrics that are valid for your industry, such as inventory turns, job costing reports, days to market, customer returns, utilization rates, etc. Providing organizational charts and competitive industry details is also valuable.
3. Just as important as preparing your loan request package, give serious evaluation to the bank and banker you want to work with. In today’s market, financial institutions vary widely. Consider what is important to you: branch convenience, technology and services, commercial focus and approval process, legal lending limit, ability for the bank to grow with you over time, etc. Think about whether these needs are best met by working with a large national institution, a strong regional player, or a small community bank. Once you have a sense of the type of institution that would best fit your business, research to determine the best contact at that bank for you. Most commercial banks have several bankers in one department with a manager above them. Finding the right person and personality for you to build a long-lasting relationship with can make all the difference in the growth of your business over time, particularly through the tough years.
The classic 5 C’s of Credit have been an excellent guide for many over the years on the borrowing process. If you can imagine yourself in the shoes of the banker, thinking through their concerns, it will help you prepare your request and business case.
Character
During the entire request process, the banker is also evaluating your character to try to determine if you would be a trustworthy borrower. Be sure to have your personal finances in order as well. Complete a detailed personal financial statement (any bank can provide you their form), know your credit score, and clear up any incorrect items with the credit bureaus. Provide background about your relevant experience and track record of profitability and repayment ability. This can also include any prior company experiences. Most of all, be forthcoming with both the good and any downside to your experience. Bankers never like surprises.
Capacity
You should know that the bank will be examining your financial statements and then calculating certain financial ratios. Two of the most critical ratios are leverage and debt service coverage. Leverage is measured by debt/net worth and the lower the better. While the target varies per industry, a good guideline is under 2:1. Cashflow is a measure of income/debt payments or more specifically EBITDA/(prior year’s current maturities of long term debt + interest expense). It is essential that this ratio exceeds 1.2:1.0, no matter your industry. The higher the better as you want to show the bank you have sufficient cashflow to service your debt along with a cushion for good margin.
The key takeaway: it is good if you are able to calculate these in advance so that you can anticipate how favorably your numbers will be viewed in the eyes of the bank.
Capital
This refers to your net worth or equity value in the businesswhich is determined by the value of your assets less the amount of your liabilities (how much youown minus how much you owe). The higher your net worth, clearly the better.
Note: a negative net worth is a red flag to the bank and a sign you may still be at the level of borrowing from friends and family or other non-traditional sources such as factoring receivables or venture funding.
Collateral
After the bank examines your cash flow repayment ability, they then look to collateral. Consider your business assets and personal assets you have available to offer. This may include real estate, investments, accounts receivable, inventory, equipment, and even your personal residences. How large and liquid are they in relation to the loan you are requesting? The reality is, they should be larger than your loan request as banks discount the value of most assets and only lend 40%-80% against most assets.
Conditions
If you have encountered any difficult spots in your business in the past few years, address them up front. Prepare to tell the story of your business and how you worked through the challenging times. Different banks may also have different tolerances for different industries. This may be based on the performance of the industry overall, the bank’s experience in that industry or their amount of current exposure to that industry. Ask about their preferences to find a better match and increase your success rate. Remember, no industry was untouched in the recent great recession. How you faced those challenging times will be insightful.
Seeking financing in today’s market is complex. To put your best foot forward, much preparation is needed. Seek the guidance of an advisor(s) for input into your request and positioning. Your CPA, attorney or Warren Whitney consultant can be a valuable resource in this process.
Contributor: Paul Shelley, Sr.
For over 15 years, Warren Whitney has been assisting both non-profit and for-profit clients with their human resources and staffing needs and issues. During this time, we have learned that the summer months can present staffing and productivity challenges since many employees take vacation during the summer months. The following are suggestions that we advise our clients to do (or not to do) in order to minimize staffing headaches during the summer months:
- Have a scheduling procedure, and ask employees to schedule time off as far in advance as possible. Make the departmental vacation schedule available to those in the department. Make it clear that the department must continue to operate smoothly and everyone can’t take vacation at the same time. Those who schedule vacations far in advance are those that will most likely be approved. Those who wait to make their vacation plans may find that the time-off request must be denied due to the department needs and other employees’ scheduled vacation.
- Hire high school and/or college students to work during the summer. They are not expensive, want to learn and can fill in gaps in the workforce during the summer. Many organizations hire several students/interns and rotate them around to different departments as needed. The student gets a summer job, makes some money and learns some skills. The organization gets some workload relief for employees who are out on vacation. Also, the organization gets to know the student and his/her work performance/skills and may want to hire him/her for several summers, part-time work during the school year, or even for a full-time position once he/she graduates.
- Hire individuals who are willing to work on a part-time, fill-in or temporary basis. There are plenty of people, such as retirees, who would like to work some hours but not all the time. Ask your employees for referrals and/or contact some of your former employees to see if they might want to work a week or so at a time or a few days per week or month to fill in for employees on vacation. Many of these retired people and very flexible and highly skilled.
- Call a temp agency. We suggest that if you use a temp agency, use one that you have established a relationship with over time and are satisfied with the services and quality of people they provide. If you don’t have a relationship with a temp agency, start now to establish a relationship with one or two. Ask around to other organizations to determine the temp agencies they use and which ones they like best. Organizations that use temp agencies can tell you very quickly which ones they like best and which ones provide the best services, rates and assign good workers. Although Warren Whitney is not a temp staffing agency, we can provide employees for short-time, temporary assignments especially for administrative or accounting (all levels) needs.
- Provide a laptop computer, tablet or smart phone (if they don’t already have one) to an employee on vacation so that they can check emails and deal with any emergencies while on vacation. This may not be appropriate for some positions but may be highly appropriate for other positions. Some employees may not want to do this but some employees would rather do this than come back to work to find a large number of emails waiting for them and a lot of issues to deal with upon his/her return. Many of the issues are probably minor that could be passed to others to handle, or the employee can decide which ones can wait to be handled upon his/her return. At least they are keeping in touch during their vacation and will not be blindsided or overwhelmed upon their return to the office.
Paul Shelley, Director at Warren Whitney, is responsible for the Recruiting and Human Resources (HR) Practice Unit. Contact Paul at pshelley@warrenwhitney.com or at (804) 282-9566.

Contributor: Scott Warren
Businesses don’t always have a choice in their level of cash reserves, but having a target will help guide decisions regarding how to deploy cash. Deciding what that target should be depends on your business’s particular risk factors. There is no exact formula, but consider the two broad categories of revenue generation and fixed vs. variable expenses as a starting place and a range of three to six months of operating expenses for your cash reserve. If your risk in generating stable income and your fixed costs are both high, your cash reserve target should be closer to six months.
Try the following approach to get a sense of what type of cash reserve target you should have.
1. Start your analysis by identifying and assessing your revenue risks. These risks could include factors such as:
a. Diversity of revenues – Greater diversity equals lower risk. Consider various types of diversity, including industry, size of company, location, etc.
b. Concentration of revenue – This is the flip side of diversity of revenues. If a large percentage of your revenue comes from one source, your risk is higher.
c. Margin associated with revenue line items – Greater margins equal lower risks.
d. Control over revenue – Is your product or service necessary or optional for your customers?
e. Length of contracts – Do you have contracts? Do they span months / years? What are the terms of cancellation?
f. Market share – How likely is it that your organization will be on the “short list” as customers make their decisions.
g. Economy – How is the economy – local, national or international – based on where you draw customers?
h. Trends – Does your crystal ball show that things are getting better or worse?
i. Accounts receivable – Are you a cash business? Will you be able to collect your accounts receivable?
2. Next, identify and assess your fixed versus variable costs. More fixed costs mean higher risk because you cannot make adjustments as quickly and, therefore, a higher cash reserve target is appropriate. Consider:
j. Type of expense – Examine your fixed short-term vs. long-term expense commitments.
k. Debt service – How much do you have to pay to stay current, and what is that as a percentage of total expenses?
l. Long-term leases – Again, what are the fixed payment commitments?
m. Staff – Can you cut staff if you lose contracts? How fast are you willing to cut staff if there’s a downturn?
n. Corporate overhead – What other overhead costs are essentially fixed?
o. Variability of expense – Examine the flexibility of expense levels for different business units.
3. Finally, plot your risk assessment on a matrix where one axis represents revenue risks and the other represents fixed cost risks. See an example below.
Example of Completed Cash Reserve Matrix
Suggesting a Reserve Equal to Two Months of Expenses
(letters indicate risk factors listed above)
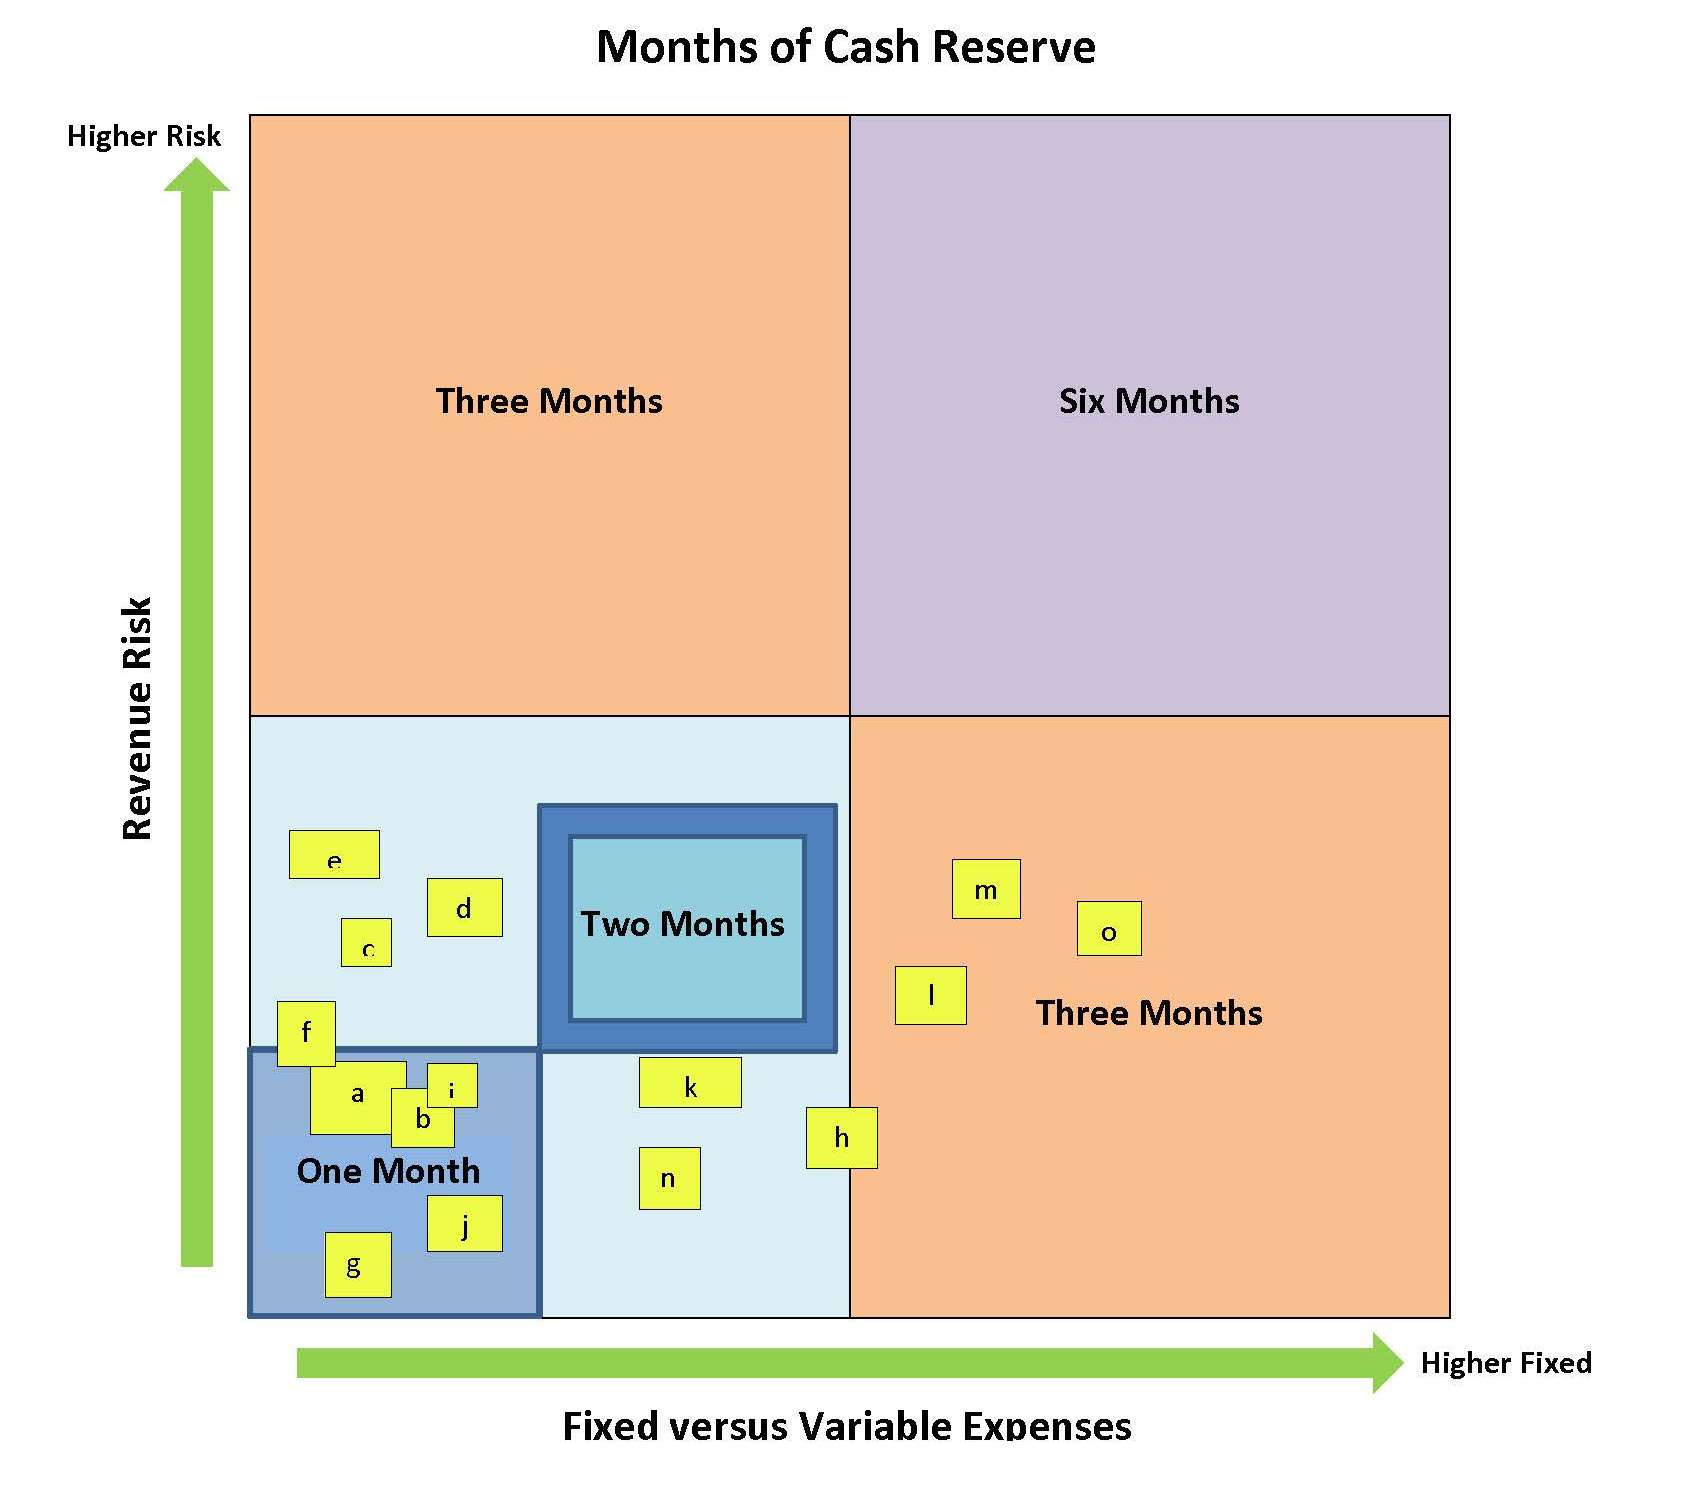
This methodology should provide structure to support to your estimation of cash reserves.
Contributor: Mallory Lundy
From a widespread and environmental incident such as Hurricane Sandy in 2012 to an isolated event like the sudden death or absence of an employee, there are many possible causes for a disruption of business. Because of this, it is beneficial to have a plan in place before an incident occurs so that your business experiences as few disruptions as possible. While not all business disruptions are foreseeable or preventable, there are key elements to include in each business continuity plan. Warren Whitney’s Mallory Lundy offers some general advice on where to begin.
1. Know the key operations and key operators. It is vital to identify the essential operations needed to keep the business running, as well as the people needed to perform these tasks. Remember to cross-train for essential functions.
2. Keep original files onsite.
a. Original company files will need to be accessible in the event of an emergency; therefore, they should not normally be kept at an employee’s home.
b. Make sure there is an electronic copy of each original document in case the hard copy should become lost or damaged. Keeping the electronic copy saved in multiple places and backed up offsite will provide extra peace-of-mind.
3. Perform regular back-ups. Any important information (e.g., accounting files) should be backed up off-site so that they can be accessed from another location in case a place of business cannot be reached. Be sure to perform these back-ups regularly. The cloud may be a beneficial tool. As an added precaution, also ensure you have applications on machines offsite as well to restore and run the data. This is especially important if you have legacy systems.
4. Identify an alternate work location.
a. Should a hurricane, snow storm, fire, or other event prevent you and your employees from reaching your place of business, have an alternate location identified in your contingency plan. This will cut down on losses from disruption of business.
b. Consider allowing employees to continue with key operations from their home when appropriate.
5. Create an employee absence manual.
a. This manual should include all of the information necessary for operations to continue in the event an employee is suddenly unable to perform his/her duties.
b. Define employee job descriptions with a detailed explanation of each task the employee performs. The task list should include important deadlines and where to find essential account passwords.
c. Identify who should handle an employee’s responsibilities in the event he/she cannot return to work.
6. Centralize contact information.
a. Update contact information frequently and redistribute the information on a regular basis, especially when gaining a new employee.
b. While traditional contact mediums are useful some companies may decide to use avenues such as social media to communicate during disruptions.
c. Consider whether you could need access to customer or vendor contact information and determine the best way to access and safeguard that information.
7. Inform all employees. All employees, including new hires, should understand the business continuity plan, their roles and how to communicate in the event of a disaster, prolonged employee absence, or other disruptive event.
8. Perform a regular review.
a. In some cases, documents and procedures will need to be updated on a rolling basis or perhaps quarterly or bi-annually. However, ensure that at least annually the plan and all documents are reviewed and practices, procedures, and documents are up to date.
b. If certain daily operations are essential to business continuation, perform disaster drills to test the preparedness and effectiveness of the business continuity plan, including testing the restore from back-up routine for each mission critical application.
9. Consider insurance. Evaluate, or review, business interruption insurance coverage annually with your insurance agent to discern if coverage makes sense based on the particulars of your business model.
While these measures take time, in the event of a crisis, your planning will prove beneficial.

 Data Directions Inc.